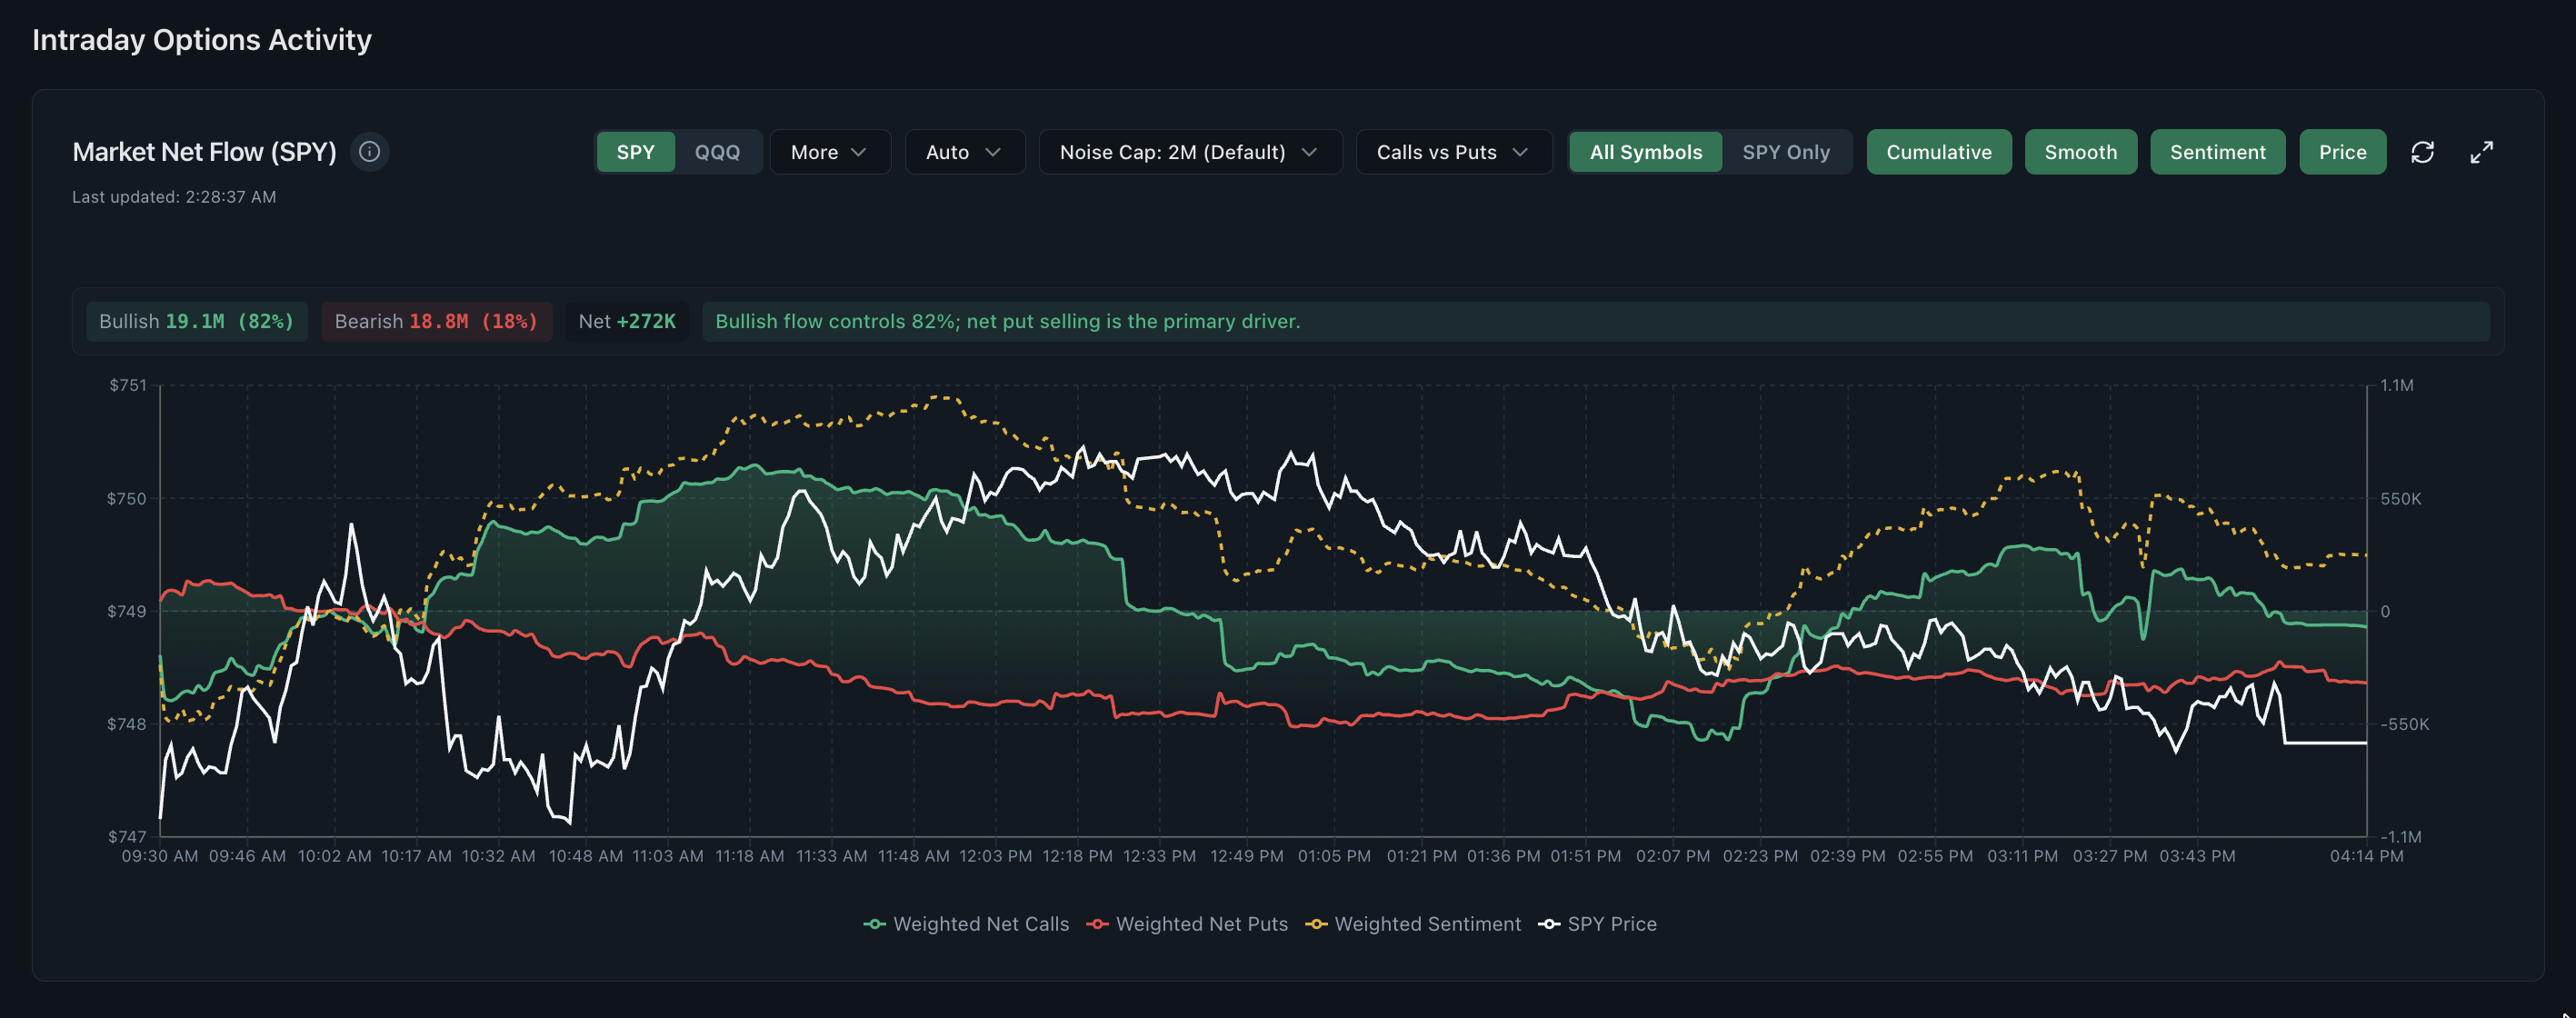


Premium versus contract count
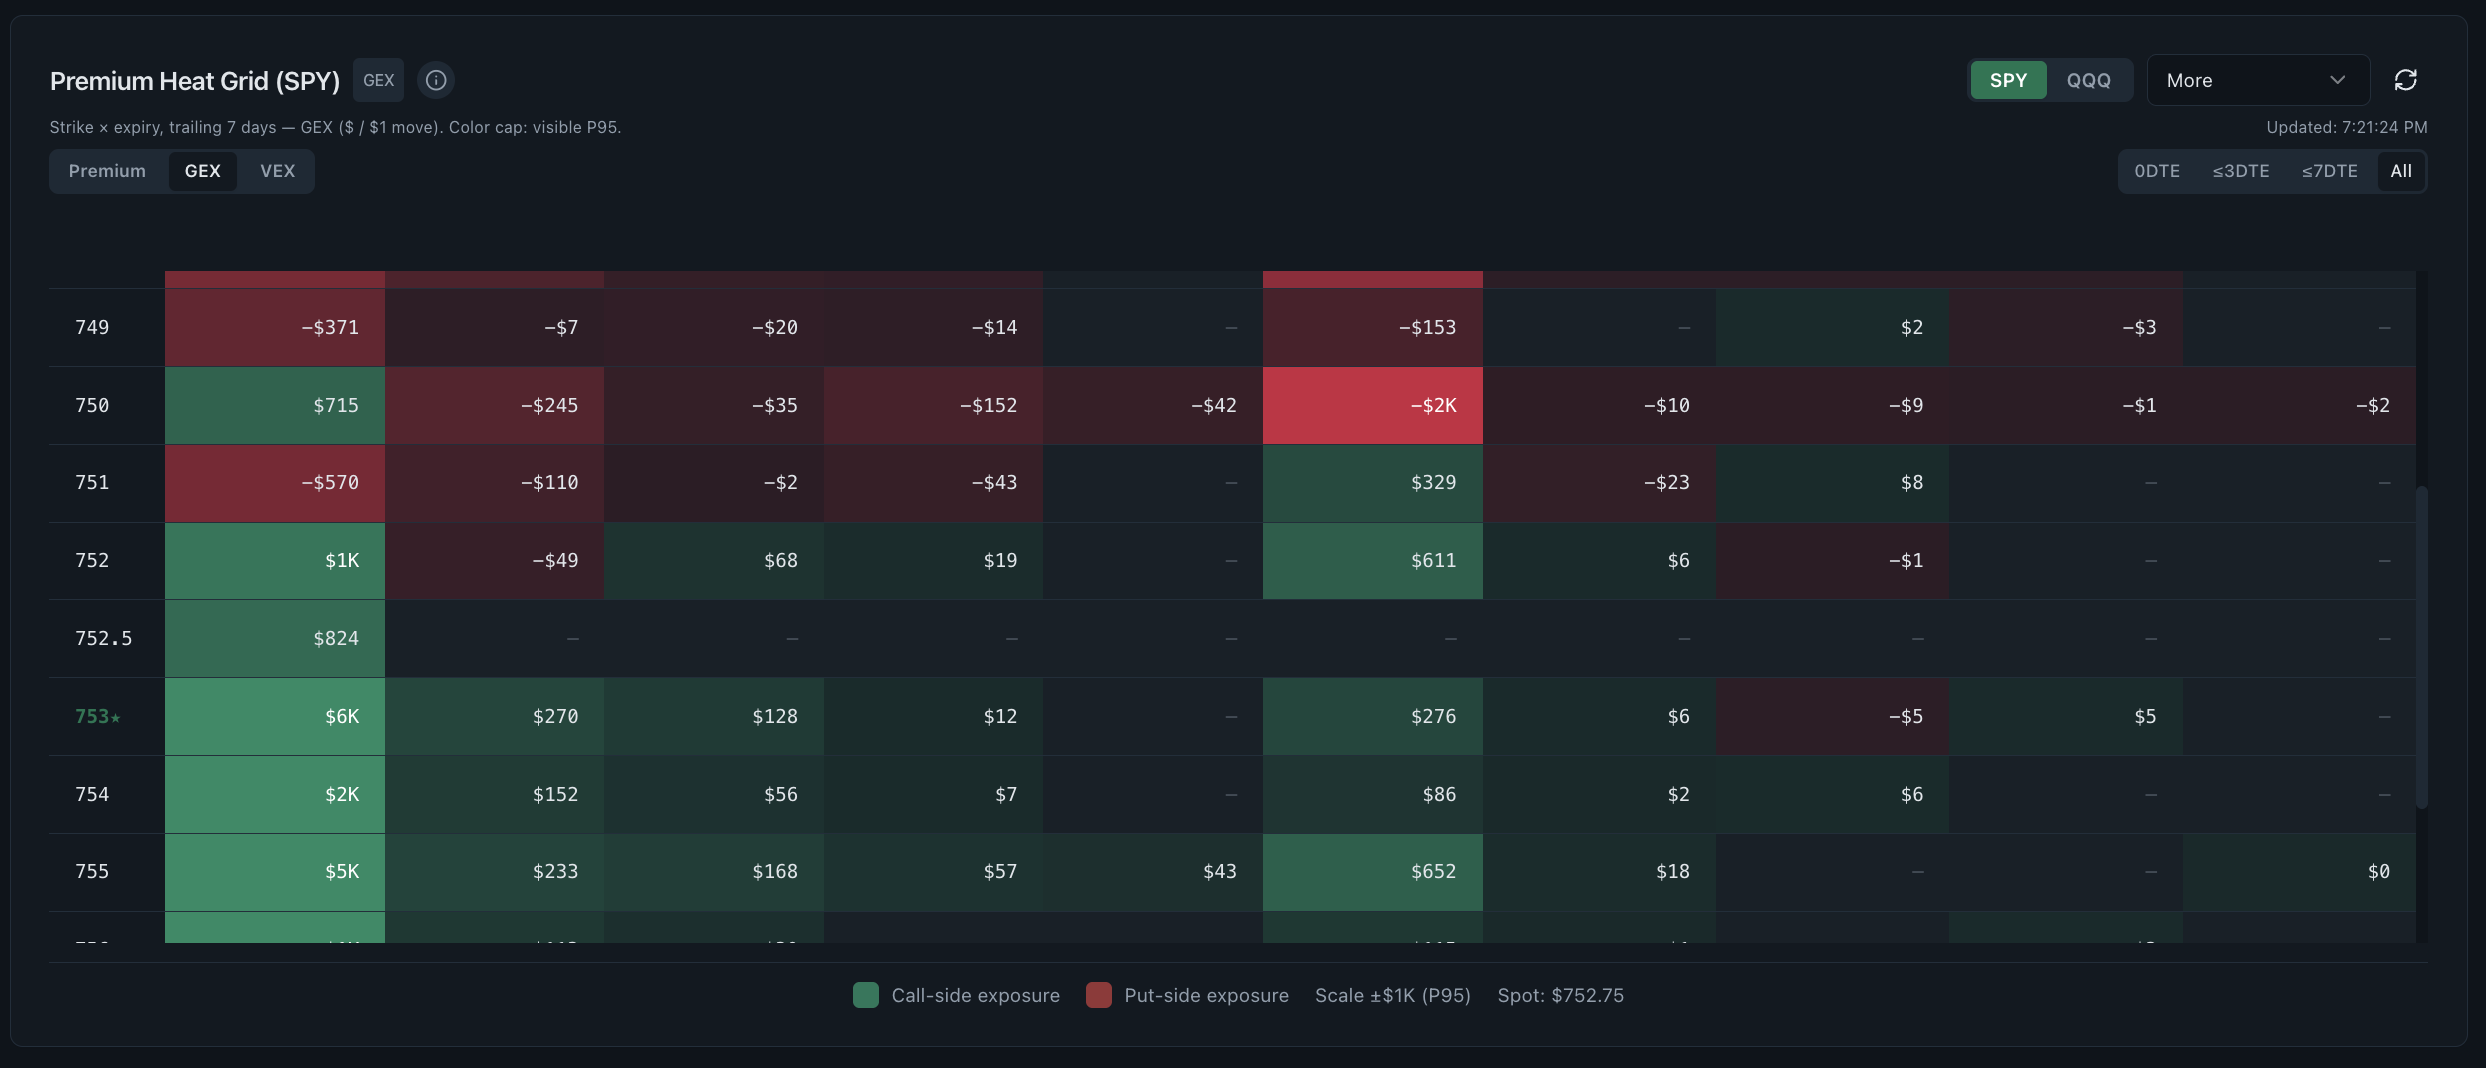
Premium is a more honest measure of options activity than contract count because contracts are not comparable units. Premium is contracts multiplied by the option price multiplied by the 100-share multiplier, so it states the money that changed hands. Two prints of 2,000 contracts, one in a cheap same-day strike and one in a long-dated strike, can differ in committed premium by more than eighty times while a contract-count leaderboard shows them as equal.
- Formula
- Premium = contracts x option price x 100
- Worked gap
- 2,000 contracts at $0.35 versus at $28.40 differs by about 81 times
- Contract-count bias
- Rankings drift toward the cheapest contracts available
- Premium is not
- Net risk, net direction or money at stake for one side
- Third measure
- Notional, which uses strike rather than option price
How is options premium calculated?
Premium is the option price multiplied by the number of contracts multiplied by the 100-share multiplier. The two illustrative cases below use identical contract counts and produce results that are not remotely comparable. These are arithmetic examples chosen to make the mechanism visible, not observed trades from any session.
Read the supporting context
The ratio between them is about 81 to 1. A ranking that sorts by contracts places these two side by side; a ranking that sorts by premium places one of them 80 rows above the other, and only one of those layouts reflects the money involved.
| Illustrative print | Premium committed |
|---|---|
| 2,000 same-day calls at an option price of $0.35 | 2,000 x 0.35 x 100 = $70,000 |
| 2,000 long-dated calls at an option price of $28.40 | 2,000 x 28.40 x 100 = $5,680,000 |
| Contract count for both | 2,000, identical |
| Ratio of premium committed | About 81 to 1 |
| What a contract-count ranking reports | A tie |
Why do contract-count leaderboards favour cheap contracts?
For a fixed budget, cheaper contracts buy more of them. A participant spending a given amount on a low-priced short-dated strike generates a far larger contract count than the same amount spent on an expensive long-dated one. Rank by contracts and you have built a ranking that systematically rewards the cheapest part of the chain.
Read the supporting context
This produces a familiar problem: the same liquid names dominate the leaderboard while larger money commitments sit further down the page. The ranking is not broken. It is measuring something different from what many readers expect.
- Cheap contracts inflate counts for any given amount of money committed.
- Short-dated expiries are usually the cheapest part of the chain, so they dominate count-based rankings.
- High-priced underlyings appear less often in count rankings than their money commitment warrants.
- Deep out-of-the-money strikes look large by count and small by premium.
- A premium ranking reorders the same session substantially, which is the clearest demonstration that the two are not interchangeable.
How do premium, notional and net risk differ?
Premium is not the only money-denominated measure, and the three in common use answer different questions. Confusing them produces figures that are wrong by orders of magnitude, usually in the direction that sounds more impressive.
Read the supporting context
Notional in particular is often quoted where premium is meant. Notional describes the size of the underlying exposure the contracts reference; premium describes what was paid or received for them. For an out-of-the-money option those two can differ by a factor of hundreds.
| Measure | What it states |
|---|---|
| Contract count | How many contracts transacted; not comparable across strikes or expiries |
| Premium | Contracts x option price x 100; the money that changed hands on the trade |
| Notional | Contracts x 100 x strike or spot; the size of the underlying exposure referenced |
| Net risk | Not derivable from a public print at all; depends on the rest of the participant's book |
Why is premium still an incomplete measure?
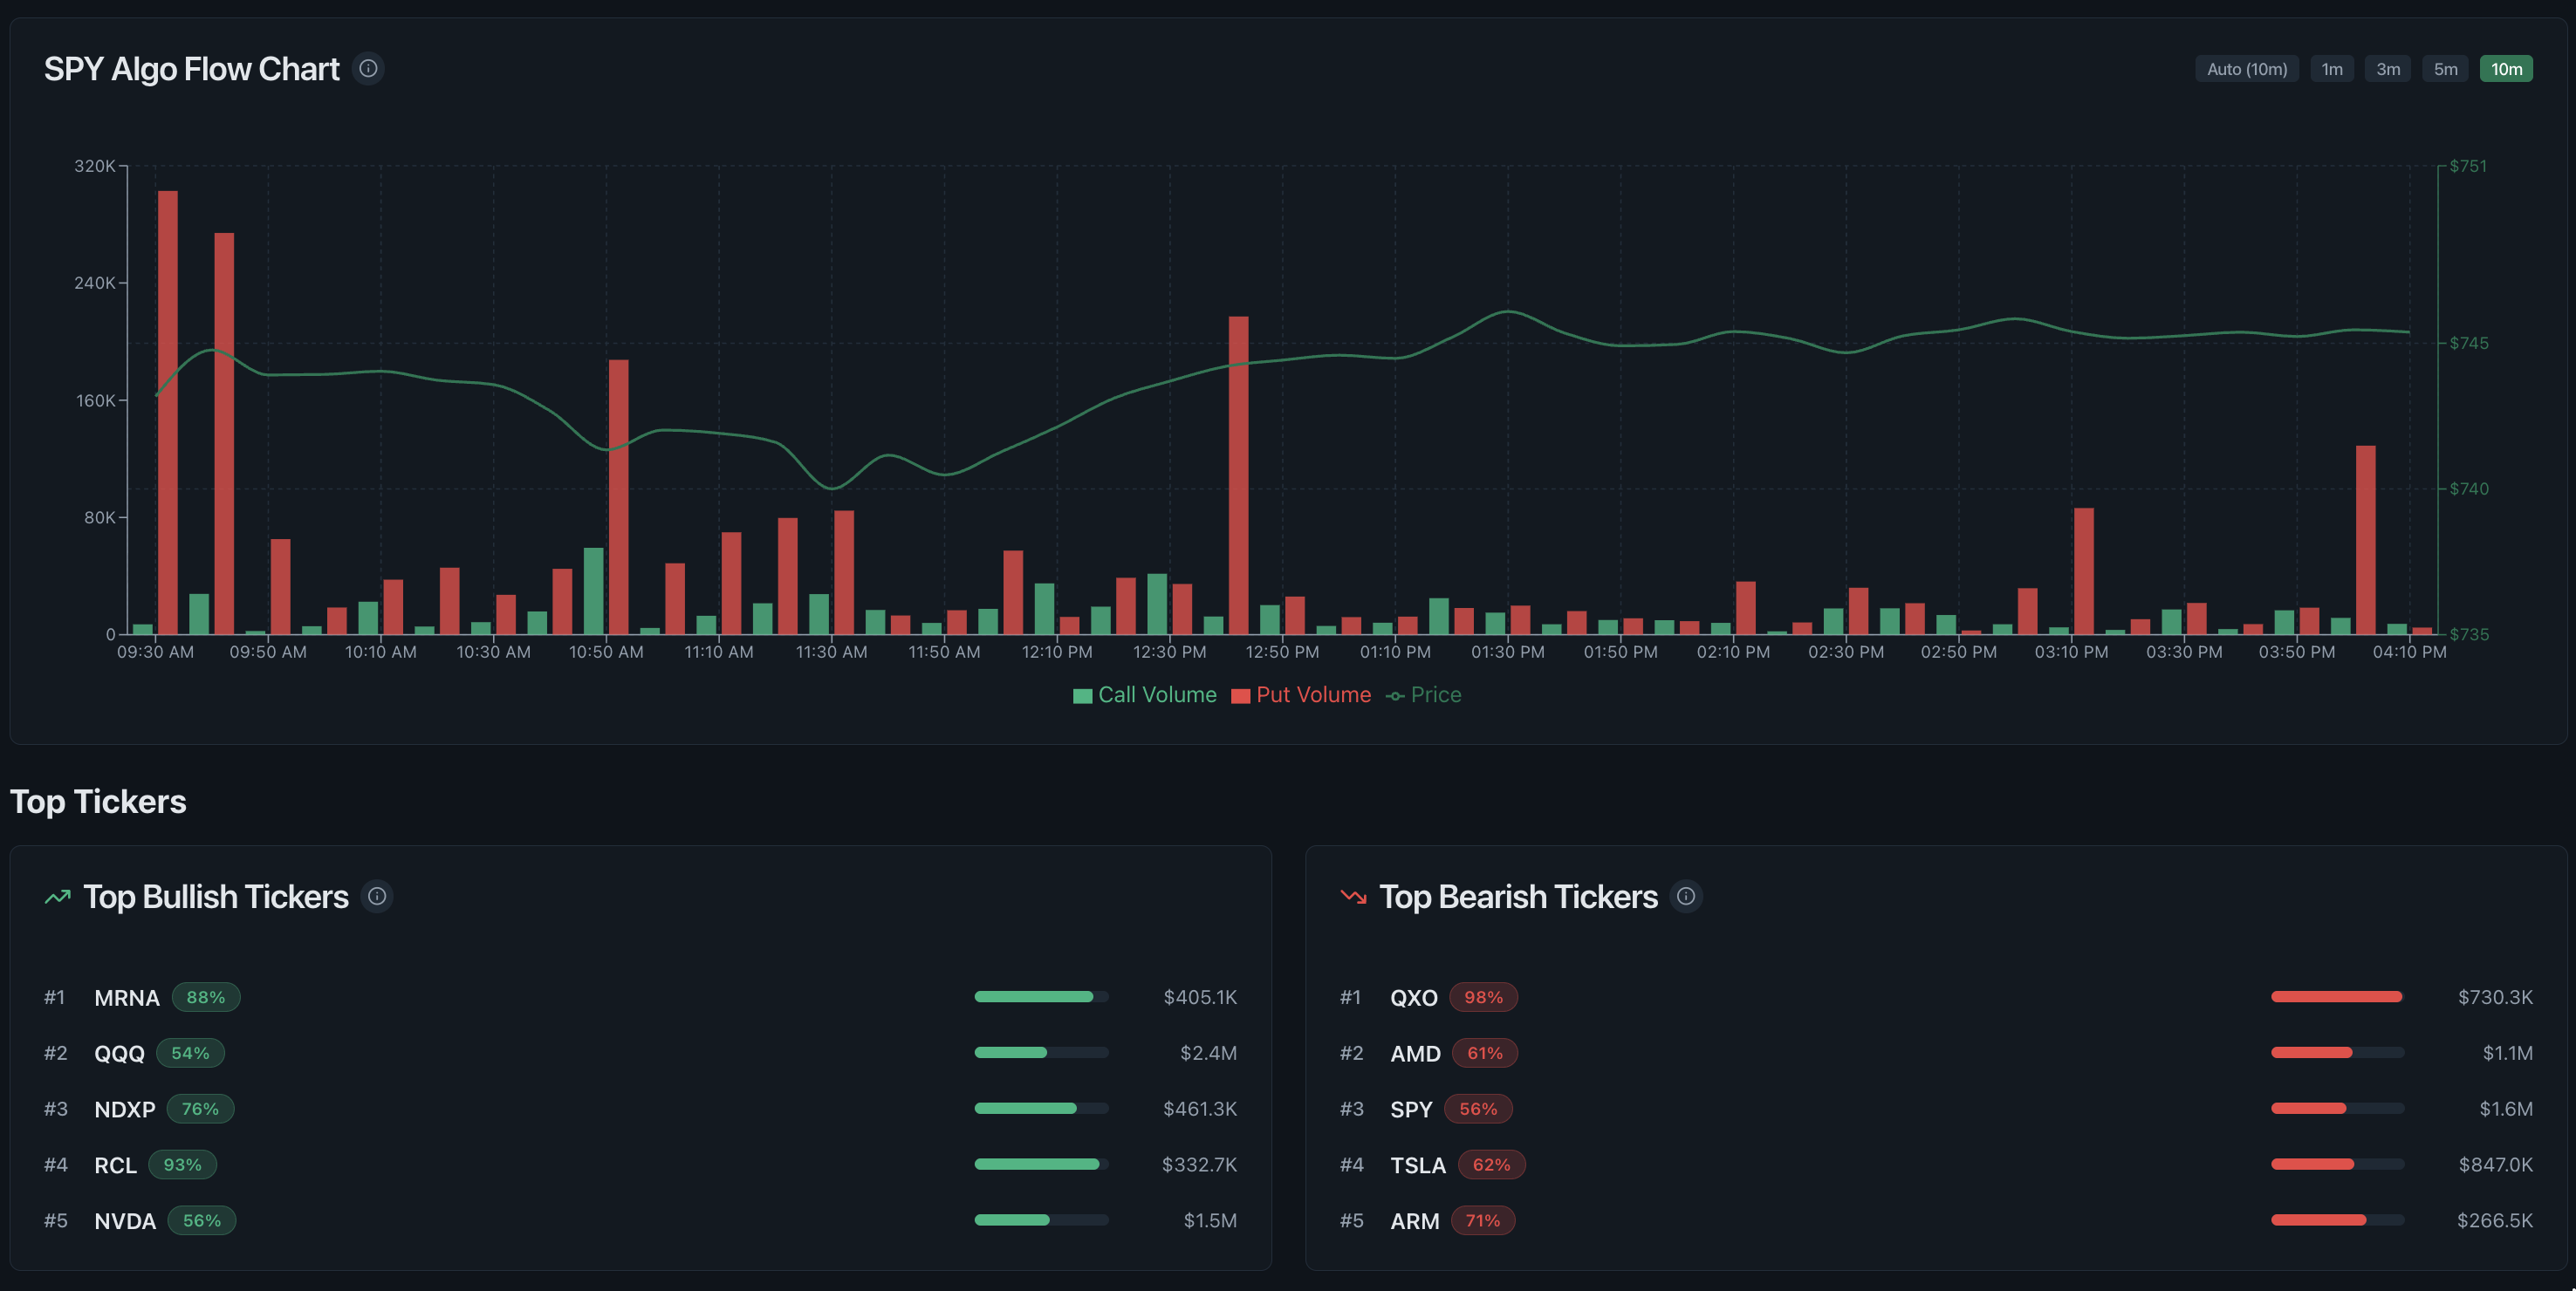
Premium is better than contract count and still limited. It records money that changed hands, which means both the buyer and the seller are represented by the same figure. A large premium number says a large amount of money moved, not that a large directional bet was placed.
Read the supporting context
Multi-leg structures compound this. A collar, a vertical spread or a roll generates premium on each leg, and if the legs print separately the total premium attributed to the ticker can substantially overstate the net money committed to the position. Selling one leg to finance another is a common structure whose net cost is a fraction of its gross premium.
- Both sides of every trade contribute to the same premium figure.
- Spread legs printing separately inflate ticker-level premium relative to net commitment.
- Closing trades add premium in the opposite economic direction to the original position.
- Premium says nothing about leverage, margin used, or risk retained after hedging.
- A high-premium print is a research prompt, not evidence of an attractive contract.
How can researchers rank a session without assigning meaning?
A ranking is a way of allocating attention, and it should be judged on whether it surfaces things worth checking rather than on whether it looks decisive. The sequence below produces a shortlist while leaving interpretation entirely open.
Read the supporting context
Realtime Options ranks by premium and shows contract count, trade count, strike, expiry and open interest alongside it, so the composition of any headline number stays visible. It does not screen by implied volatility rank or percentile, does not screen contracts by premium yield for covered calls or cash-secured puts, and does not present any ranking row as a recommendation.
- Rank by premium so the units are comparable across the board.
- Display contract count and trade count next to it so the composition is visible.
- Compare each entry against its own recent baseline rather than a market-wide threshold.
- Check the next settled open-interest change before treating premium as new positioning.
- Look for a second leg before attributing the full premium to one directional view.
What can options premium not tell you?
Money committed is a scale measure, not a direction or a quality measure. A large premium figure is compatible with an aggressive directional position, a routine hedge, a market maker offsetting inventory and a fund rolling an existing structure into a later expiry. All four move the same number.
Read the supporting context
The measure also carries no information about who committed the money. Public options prints do not identify the beneficial owner, and describing large premium as smart money adds a certainty the data does not contain.
- Premium does not indicate direction, since buying and selling both register.
- Premium does not indicate skill, information or expected outcome.
- Premium does not identify the participant or their broader portfolio.
- Premium is not net risk; hedges and offsetting legs are invisible in the figure.
Common questions
How is options premium calculated?
Premium for a trade is the option price multiplied by the number of contracts multiplied by the 100-share multiplier. A print of 2,000 contracts at an option price of $0.35 represents $70,000 of premium; the same 2,000 contracts at $28.40 represent $5,680,000.
Why do premium and contract-count rankings show different tickers?
Because cheaper contracts produce higher counts for any given amount of money. A contract-count ranking systematically favours low-priced short-dated strikes, while a premium ranking reflects the money that actually changed hands, so the same session reorders substantially between the two.
Is premium the same as notional value?
No, and the two are frequently confused. Premium is what was paid or received for the contracts. Notional is contracts multiplied by 100 and by the strike or spot price, describing the size of the underlying exposure referenced. For an out-of-the-money option the two can differ by a factor of hundreds.
Does high premium mean smart money is buying?
No. Premium records money changing hands on both sides of the trade, and public prints do not identify the beneficial owner. Large premium is equally consistent with a hedge, a roll, market-maker inventory management and a directional position, so smart money adds certainty the data does not contain.
Does premium tell me whether a position was opened?
No. Only the change in open interest addresses that, and it is published once daily after the close by OCC. Large premium with unchanged open interest at the series is consistent with exposure transferring between participants rather than new positioning being created.
Should I screen options by premium yield or implied volatility rank?
Those are legitimate screens, but Realtime Options does not provide them. It has no implied volatility rank or percentile screening and no premium-yield screening for covered calls or cash-secured puts. Its premium views describe money committed in observed flow rather than filtering the chain by expected income.