

Reading put flow without assuming bearish
Put volume is not a bearish measure, because at least four unrelated trades produce it. A bought put can be a directional bearish position or protection sitting underneath stock the trader intends to keep. A sold put is usually a bullish or income position. A collar prints a put and a call together. A roll prints in two expiries at once. Strike, expiry, size and where the print landed against the spread narrow the possibilities; nothing in public options data closes them.
- Put volume includes
- Buying, selling, collars, rolls and closing trades
- Bullish put activity
- Put selling, which adds to put volume identically
- Narrowing fields
- Strike, expiry, size, quote location and paired prints
- Never observable
- Whether stock or futures sit behind the position
- Product limit
- No strategy builder and no payoff diagrams in Realtime Options
How can four put trades look identical in a flow feed?
Every option contract has a buyer and a seller, so a put print is one of four positions rather than one direction. The feed records the contract, not who initiated it or what else they hold. Two of these four are not bearish at all, and a third is bearish only in the narrow sense that it pays off if price falls while its owner is deliberately staying long the stock.
Read the supporting context
Holding these four in mind is the whole method. Everything that follows is about which of them a given print is less likely to be.
| Put position | What it usually expresses |
|---|---|
| Long put, outright | A directional view that price falls, with loss limited to the premium paid |
| Long put, held against stock | Protection under a position the owner intends to keep; a floor, not a bearish call |
| Short put, cash-secured or naked | A bullish or neutral income position; willingness to own lower, with substantial downside risk |
| Put as one leg of a collar or spread | Part of a structure whose direction depends on the other leg, not on this print |
Why can put buying rise while the underlying price rises?
Protective put buying is systematic for many holders and tends to increase when portfolios are larger, not when views are more negative. The Options Industry Council describes the protective put as adding a long put to a long stock position to establish a floor under the stock's value, held by an investor who is bullish overall but concerned about a sharp temporary decline. That is an owner protecting an asset, not a participant betting against it.
Read the supporting context
The collar works the same way with a call written to offset the cost, which is why put and call activity often appears together in the same names at the same time. A feed that reads put premium as bearish pressure will report these as negative sentiment in precisely the situations where the position is bullish overall.
- Protective puts scale with the size of the underlying position, not with the strength of a view.
- Collars print a put and a call together and are neutral to moderately bullish in intent.
- Scheduled events produce routine protective buying with no directional content.
- Closing a previously bought put also adds to put volume, in the opposite direction to the original trade.
How do strike and expiry narrow a put-flow reading?
Strike and expiry are the cheapest discriminators available, because different purposes cluster in different parts of the chain. They shift probabilities rather than settling anything, and every pattern below has a legitimate counter-example.
Read the supporting context
The useful habit is to state the strike and expiry before stating the interpretation. Reversing that order lets a directional label pick the evidence that supports it.
| Where the put sits | Explanations it makes more or less likely |
|---|---|
| Far out of the money, long dated | More consistent with tail protection or a collar leg; less consistent with a short-term directional bet |
| Near the money, short dated | More consistent with directional or gamma-driven activity; also where hedges get adjusted |
| At a round number with existing open interest | More consistent with adding to or closing an established position |
| In an expiry that spans a scheduled event | More consistent with event hedging; direction is weak evidence here |
| Paired with a call at a higher strike, same expiry | More consistent with a collar than with an outright bearish position |
What can quote location tell you, and where does it stop?
A trade near the ask is commonly classified as buyer-aggressive and a trade near the bid as seller-aggressive. That classification is an estimate of who crossed the spread, and it is the single most over-read field in options flow. Midpoint executions are markedly less directional and often appear in negotiated or multi-leg activity, which is exactly where multi-leg structures print.
Read the supporting context
Wide spreads degrade the estimate further. In a thin chain, the difference between the bid and the ask can exceed the information content of where a print landed, so the classification becomes close to arbitrary.
- Near the ask: consistent with a buyer crossing the spread, on either a bearish position or a hedge.
- Near the bid: consistent with a seller crossing the spread, which for puts is often a bullish or income trade.
- At the midpoint: weak directional information, and a common signature of spread and negotiated activity.
- Wide bid-ask spread: treat the classification as unreliable regardless of where the print landed.
How should a worked put-flow read stop short of a conclusion?
Consider a session in which a single name shows heavy put premium concentrated in one expiry, prints spread across many trades rather than one block, activity clustered slightly out of the money, and a corresponding call print at a higher strike in the same expiry. The next morning's open interest rises at both strikes.
Read the supporting context
The defensible read is that a two-legged structure was opened at those strikes, that the put and the call are more plausibly related than independent, and that the pairing is consistent with a collar over an existing stock position. The read that is not supported is that anyone is bearish. The same evidence is equally consistent with a risk-reversal, with two unrelated participants, or with a dealer hedging an over-the-counter position. Recording the alternatives is the output; picking one is not.
- Observed: premium, strikes, expiry, trade count and next-day open-interest change at both strikes.
- Estimated: which side crossed the spread on each leg.
- Inferred with caution: that the two legs belong to one structure.
- Not established: the participant, the underlying stock position, the intent or the outcome.
What ambiguity remains after every available check?
Some ambiguity is permanent, and it helps to name it precisely rather than to keep chasing it. The public tape has no field for the stock or futures position behind an option trade, and no field for the rest of the portfolio. A put that is bearish in isolation and a put that is protective are the same print.
Read the supporting context
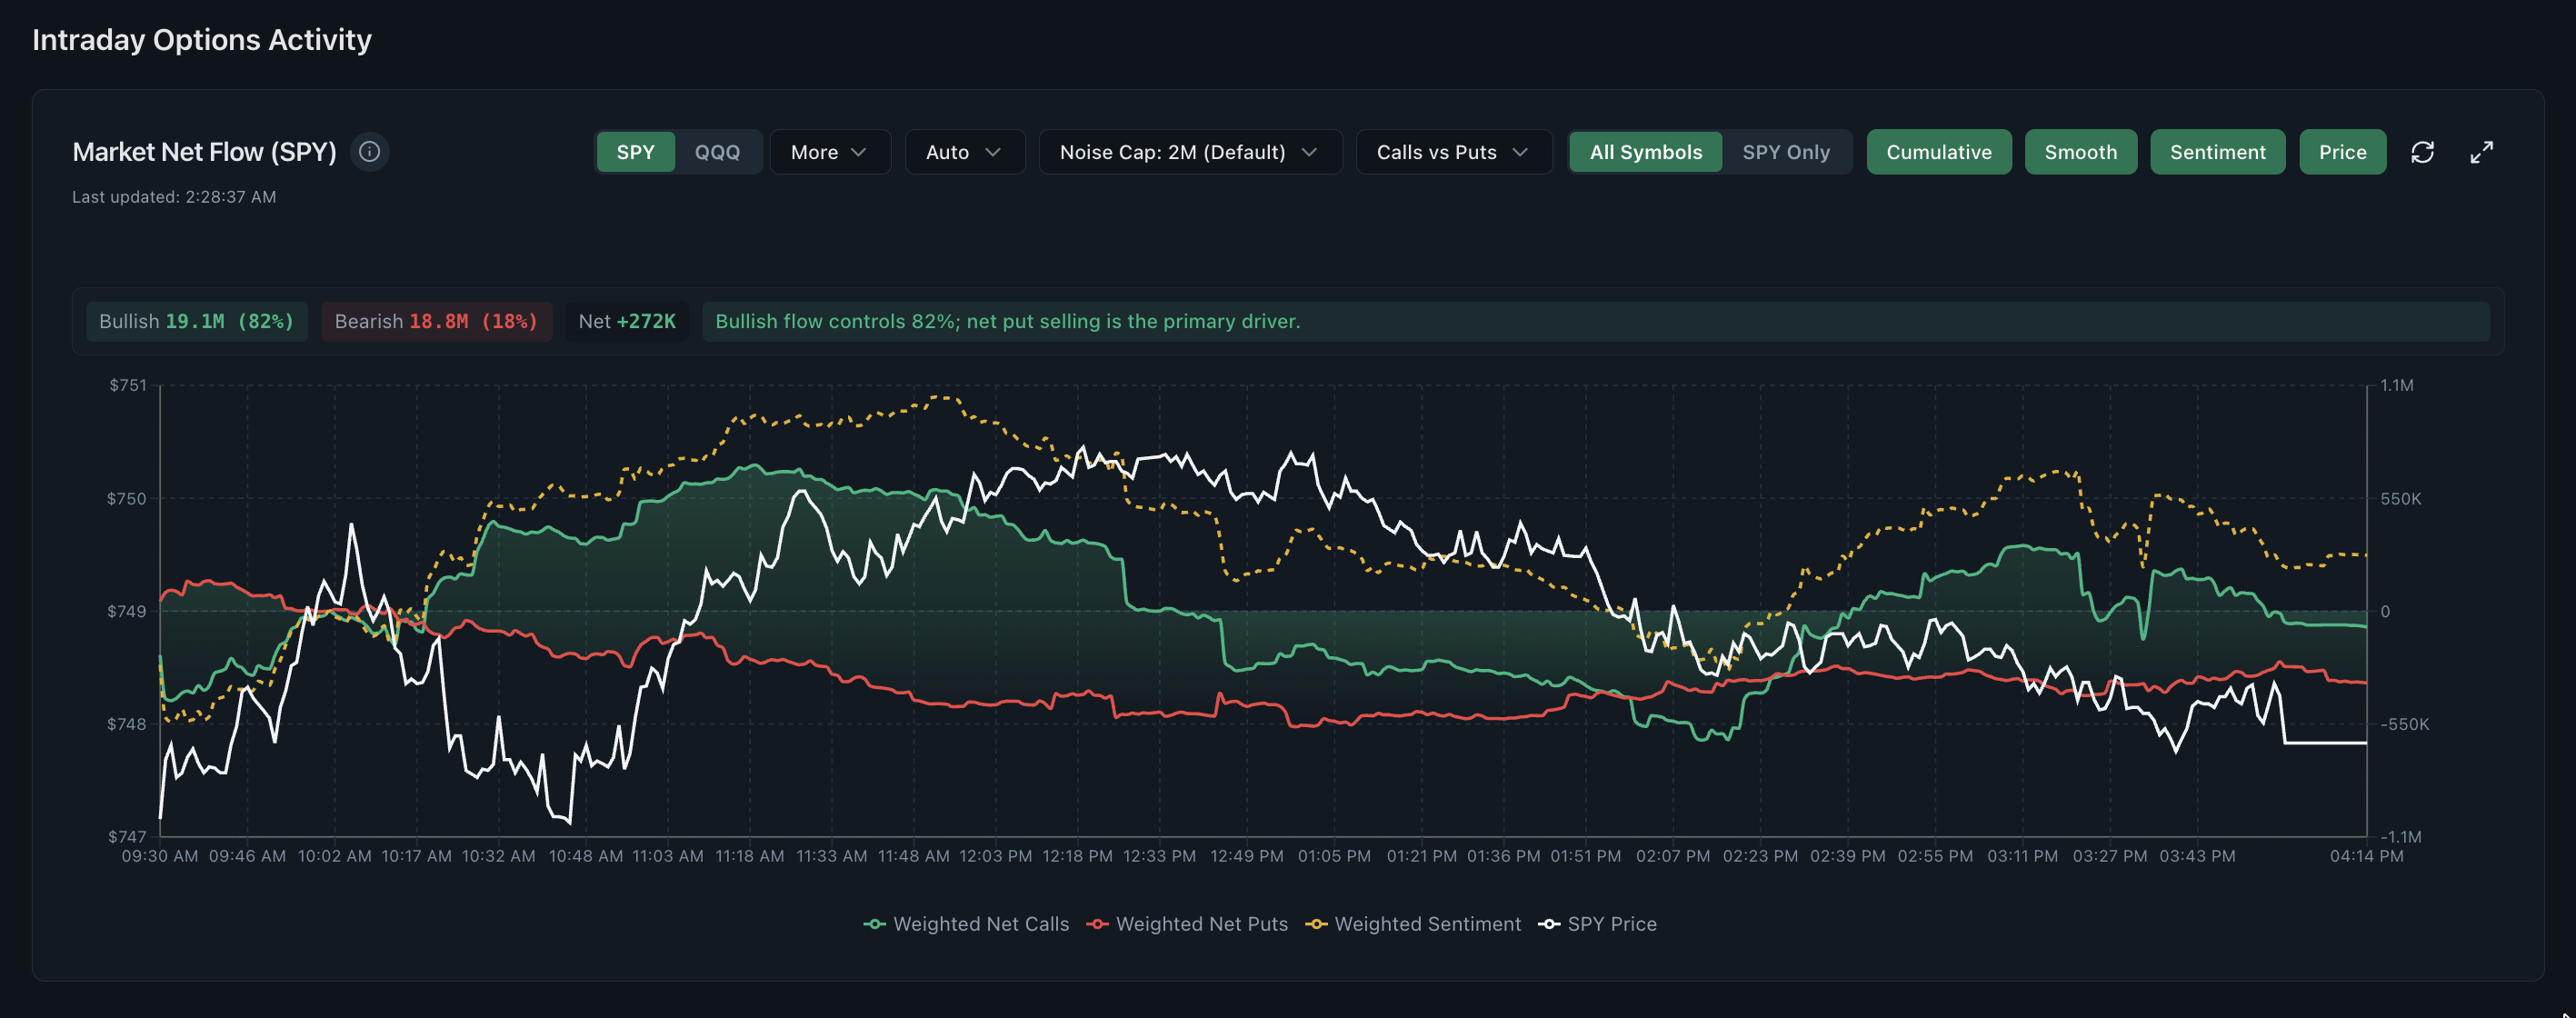
Realtime Options shows put activity by strike, expiry, premium and estimated side alongside open interest, exposure and price. It does not include a strategy builder, identify multi-leg structures with certainty or label put flow as bearish for you.
- Stock, futures and over-the-counter positions behind a print are not in the dataset.
- Legs of one order frequently print separately and can look like unrelated trades.
- A put-heavy tape can coexist with a rising market for months without either being wrong.
- Selling puts carries substantial risk that a flow feed does not display; read the OCC disclosure document before trading either side.
Common questions
Does heavy put volume mean traders are bearish?
No. Put volume counts contracts, not direction or initiator. Protective buying under a long stock position, collar legs, rolls, closing trades and outright put selling all add to the same number, and put selling is generally a bullish or neutral income position.
Can buying a put be a bullish position?
It can be part of one. An investor who is bullish overall but concerned about a sharp temporary decline may buy a put against stock they intend to keep, which the Options Industry Council describes as establishing a floor under the stock's value. The put pays off on a fall, but the overall position is long.
How do I tell put buying from put selling in options flow?
You estimate it from where the print landed relative to the bid and ask, and the estimate is weaker than it looks. Midpoint prints carry little directional information and are common in multi-leg activity, and in a wide-spread chain the classification becomes close to arbitrary.
Why does put premium sometimes rise while the stock rises?
Because protective buying tends to scale with the size of the position being protected rather than with pessimism, and because collars pair a purchased put with a written call. Rising prices give holders more to protect, so hedging demand and price can increase together without contradiction.
Does a large put print at one strike mark a level?
Not on its own. A concentration of open interest at a strike is a fact about outstanding contracts, not a level the market must respect. Gamma exposure calculated around such a strike is a model output that depends on an unobservable positioning assumption.
Does Realtime Options identify collars, spreads and rolls?
It shows the individual prints, strikes, expiries and premium that make a multi-leg structure visible to a careful reader, but it does not label structures with certainty and does not include a strategy builder or payoff diagrams. Legs of a single order often print separately and cannot be reliably reassembled from public data.