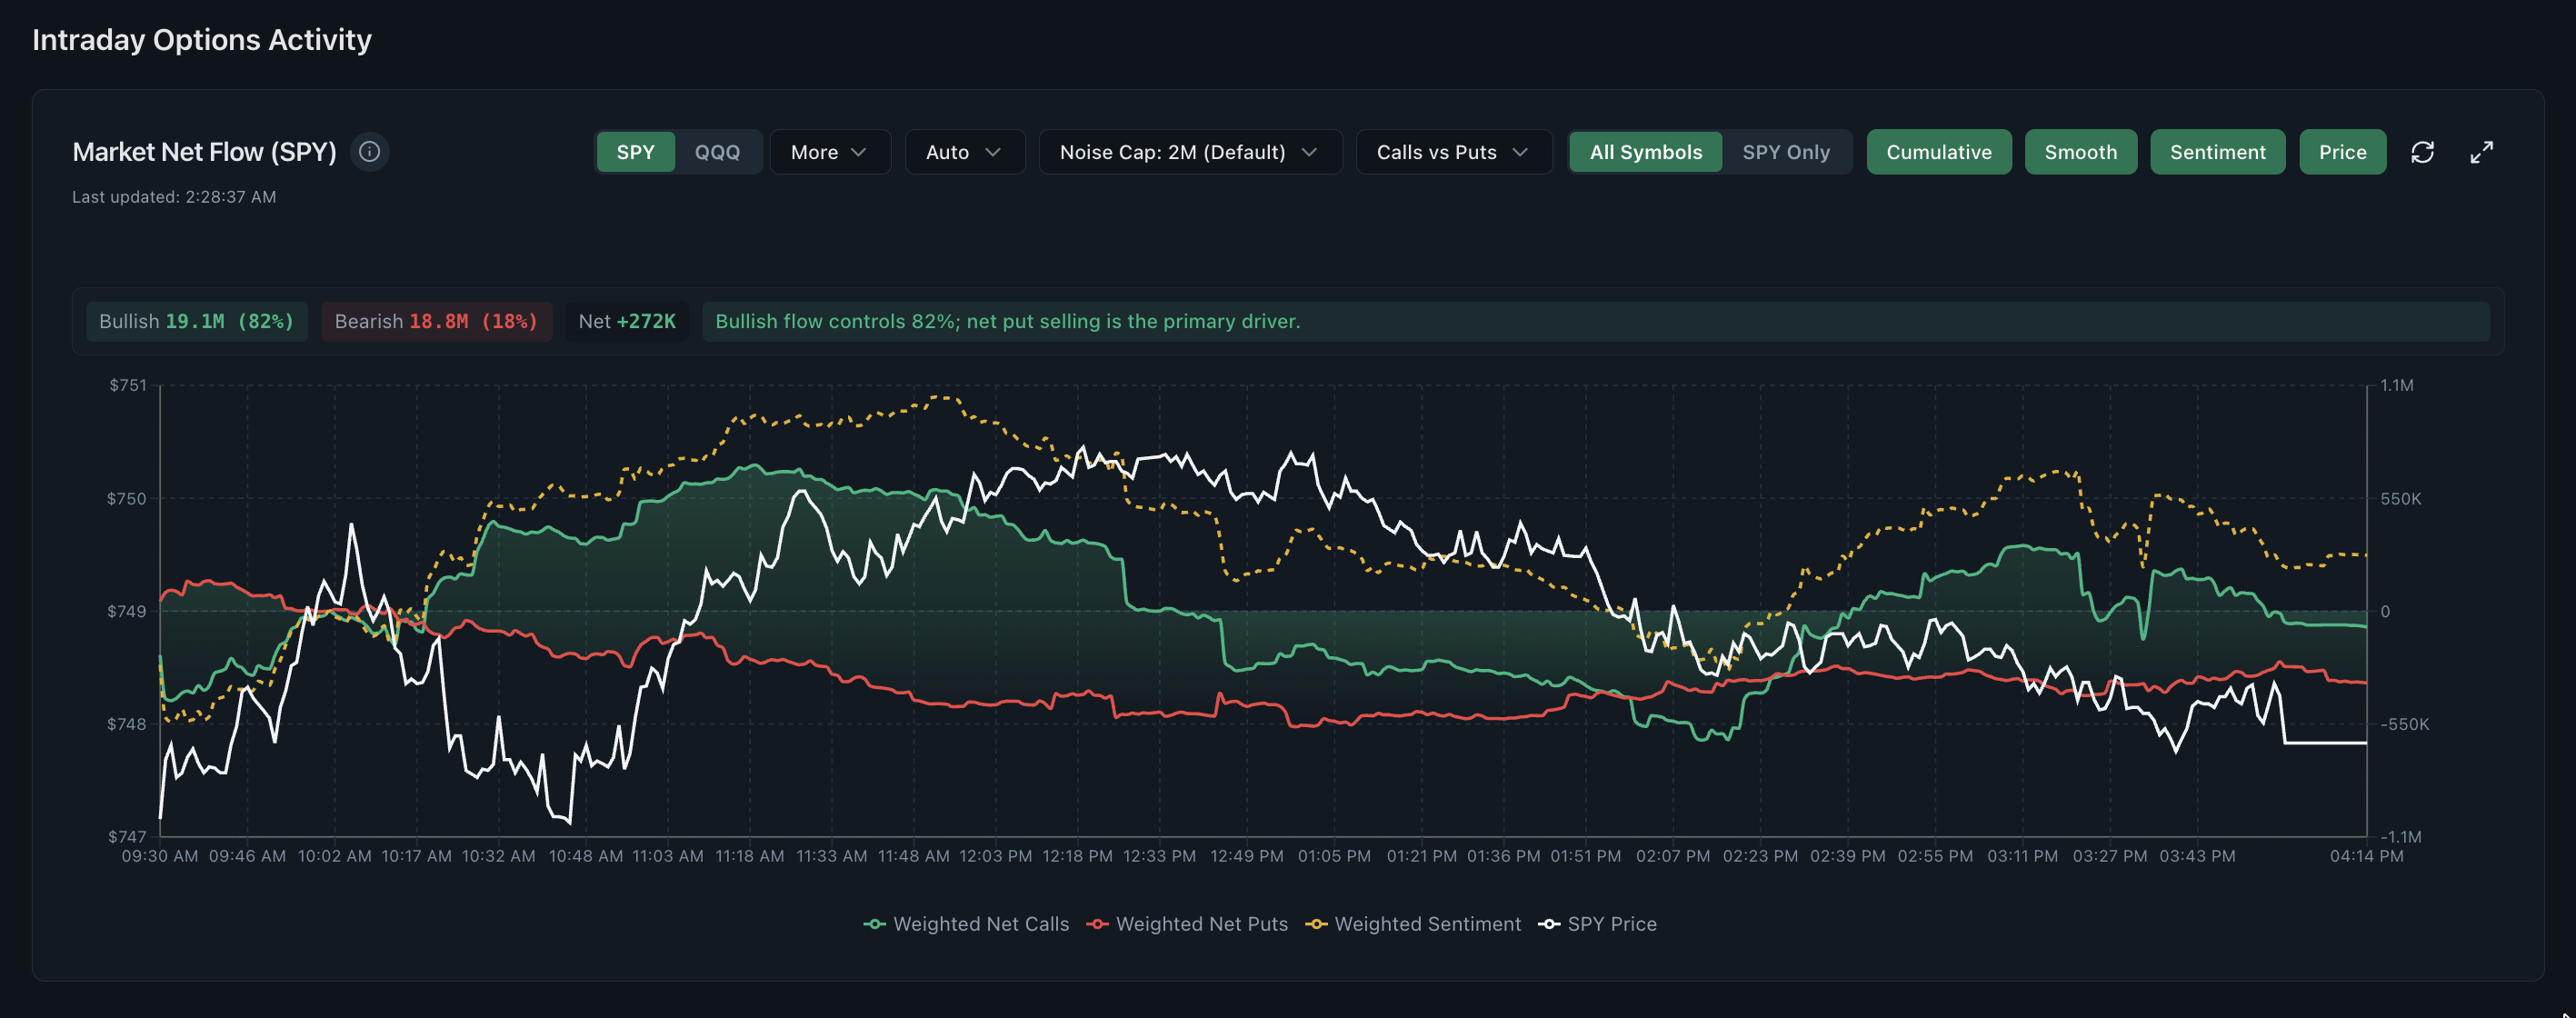


0DTE options and same-day positioning
0DTE options have zero days remaining until expiration at the time they trade. Their remaining time value can decay quickly and their delta can change sharply near the money, which makes strike, spot and gamma context especially important. The speed of the product also magnifies execution, sizing and interpretation risk.

- 0DTE
- Zero days remaining until expiration
- Primary sensitivities
- Underlying price, gamma, theta and volatility
- Research focus
- Spot, nearby strikes, exposure and actual price behavior
- Risk
- Leverage and time compression can accelerate losses
Why same-day options behave differently
A 0DTE option has little time remaining for the underlying to cross its strike. Near-the-money delta can change quickly, time value disappears through the session and a move that arrives late may not offset the decay already experienced.
Read the supporting context
This is a sensitivity and timing problem, not proof that 0DTE options move the underlying in a predictable way.
What to monitor around spot
Start with the current price and nearest strikes, then compare same-day call and put premium, open interest, estimated gamma exposure and actual intraday price response. Recalculate the relevance of a level as spot and time move.
- Distance from spot to the largest same-day exposure concentrations.
- Whether premium and contract activity repeat at the same strike.
- How the underlying behaves when it approaches or crosses the level.
- Whether scheduled macro events or expiration mechanics explain the timing.
Balanced activity and exaggerated stories
Cboe research on SPX 0DTE activity has found a broad mix of participants and substantial use of limited-risk structures. That evidence is a useful counterweight to stories that treat every same-day print as uninformed speculation or every exposure estimate as a market-control mechanism.
Read the supporting context
Product and venue differences still matter. An SPX research finding should not be copied mechanically to every ETF or single-stock option.
Common questions
What does 0DTE stand for?
It stands for zero days to expiration. The option expires at the end of that trading day under the contract's rules.
Why is gamma important for 0DTE options?
Near-the-money gamma can be high close to expiration, so delta may change rapidly as the underlying moves across nearby strikes.
Does Realtime Options recommend 0DTE trades?
No. It provides same-day flow, heat-grid and GEX analytics for research. It does not recommend contracts, entries or exits.